Which WB reports an accountant needs: the weekly sales report (this is the agent's report), UPDs for WB services, the monthly "Report on payment acceptance costs", and the acceptance and return certificates. Under the offer agreement WB sells goods in your name, so revenue equals the buyer's full payment, while WB's fee and services go on separate lines. A weekly report is approved 14 days after the week ends, so by WB's documents a month closes in the second half of the following month.
An accountant handed a new marketplace account drowns not in numbers but in documents: what to sign, which month it belongs to, what to carry into 1C. We took every document with its deadline from WB offer agreement No. 102 (in force since 1 October 2026), booked one week of a real store and checked it against 1C documentation. How to read the report itself column by column is covered in the article on the weekly report.
In short: under the offer agreement WB is an agent (cl. 3.1), and the seller's revenue is the buyer's payment, not the payout. The weekly report arrives within 7 days and, without objections, is approved after 14 days together with the services (cl. 6.7). UPDs for promotion are signed within 3 working days, and the UPD for goods WB buys out is sent within 7 days or a 20% penalty applies. Acquiring is confirmed by the monthly cost report. 1C has the "Commission agent report" and "Receipt of services" for this.
WB commission agent report: who sells to whom under the offer agreement
The buyer buys the goods from you, not from Wildberries. Clause 3.1 of the offer agreement says the seller instructs WB, for a fee, to conclude sales "in the name and at the expense of the Seller". That is an agency arrangement. Accounting software handles agents and commission agents with the same documents, hence the familiar "WB commission agent report".
| Clause | What the offer agreement says | What it means for the books |
|---|---|---|
| 3.1, 3.2 | WB sells and accepts payment in the seller's name | The revenue is all yours |
| 6.2, 6.3 | The seller pays a fee and reimburses costs | Commission and payment processing are separate expenses |
| 6.4 | Logistics, storage, acceptance and promotion are services | Separate services, not part of the commission |
| 6.7 | Services are accepted when the report is approved | The report confirms acceptance of services |
| 6.8 | VAT invoices only for VAT payers, via EDI | A VAT payer needs EDI |
| 6.9 | Mutual amounts are netted in the report | The bank shows only the difference |
Source: offer agreement on the sale of goods on the Wildberries website, version No. 102 from 01.10.2026; the contracting party is RVB LLC, TIN 9714053621
The classic beginner mistake: treating the WB payment as revenue. It is a balance after set-off (cl. 6.9), and revenue is taken from the report.
Which documents WB issues and what to do with them
Each document has its own deadline, and the seller's silence almost always counts as consent. We put them in one table.
| Document | Issued by | When | What the seller does | Clause |
|---|---|---|---|---|
| Sales report | WB | 7 days after the week | Objections within 14 days, otherwise approved | 5.5, 5.6 |
| UPD for promotion | WB | On the report timeline | Sign or object within 3 working days | 15.6.1 |
| UPD for delivery on return | WB | After the service | Sign or object within 3 working days | 11.2.6 |
| Report on payment acceptance costs | WB | Per month, up to 90 days after the banks' documents | Objections within 5 working days | 12.10 |
| Acceptance certificate | WB | Up to 10 working days after acceptance by packages | Objections within 7 days | 11.1.3, 11.1.5 |
| Return certificate | WB | Up to 30 days after the goods are handed over | Objections within 3 working days | 11.2.1 |
| UPD with marking codes | Seller | 3 working days after the acceptance certificate | Send via EDI | 4.6 |
| UPD for goods bought out by WB | Seller | 7 days, no later than month end | Send via EDI, otherwise a 20% penalty | 14.5–14.9 |
| UPD and UKD to wholesale buyers | WB in the seller's name | On sales to companies and sole traders | Register in tax records | 5.12 |
Source: WB offer agreement No. 102 from 01.10.2026
Two rows cost money. A buyout of goods by WB itself (section 14) is an ordinary sale, not an agency deal: the seller issues the UPD and pays 20% of the price in the buyout notice for being late. The second row is about wholesale buyers. If the "VAT refund to buyers" function is switched off in the account, WB stops producing VAT documents and you have to issue them yourself (cl. 5.13).
When to close the month: the WB document calendar
By WB's documents, October 2026 closes only on 14 November. The week from 26 October to 1 November crosses the month, and under cl. 5.5 WB issues two reports for it. The report for 26–31 October arrives by 7 November, and the 14 days for objections run out on 14 November. The report on payment acceptance costs may come even later.
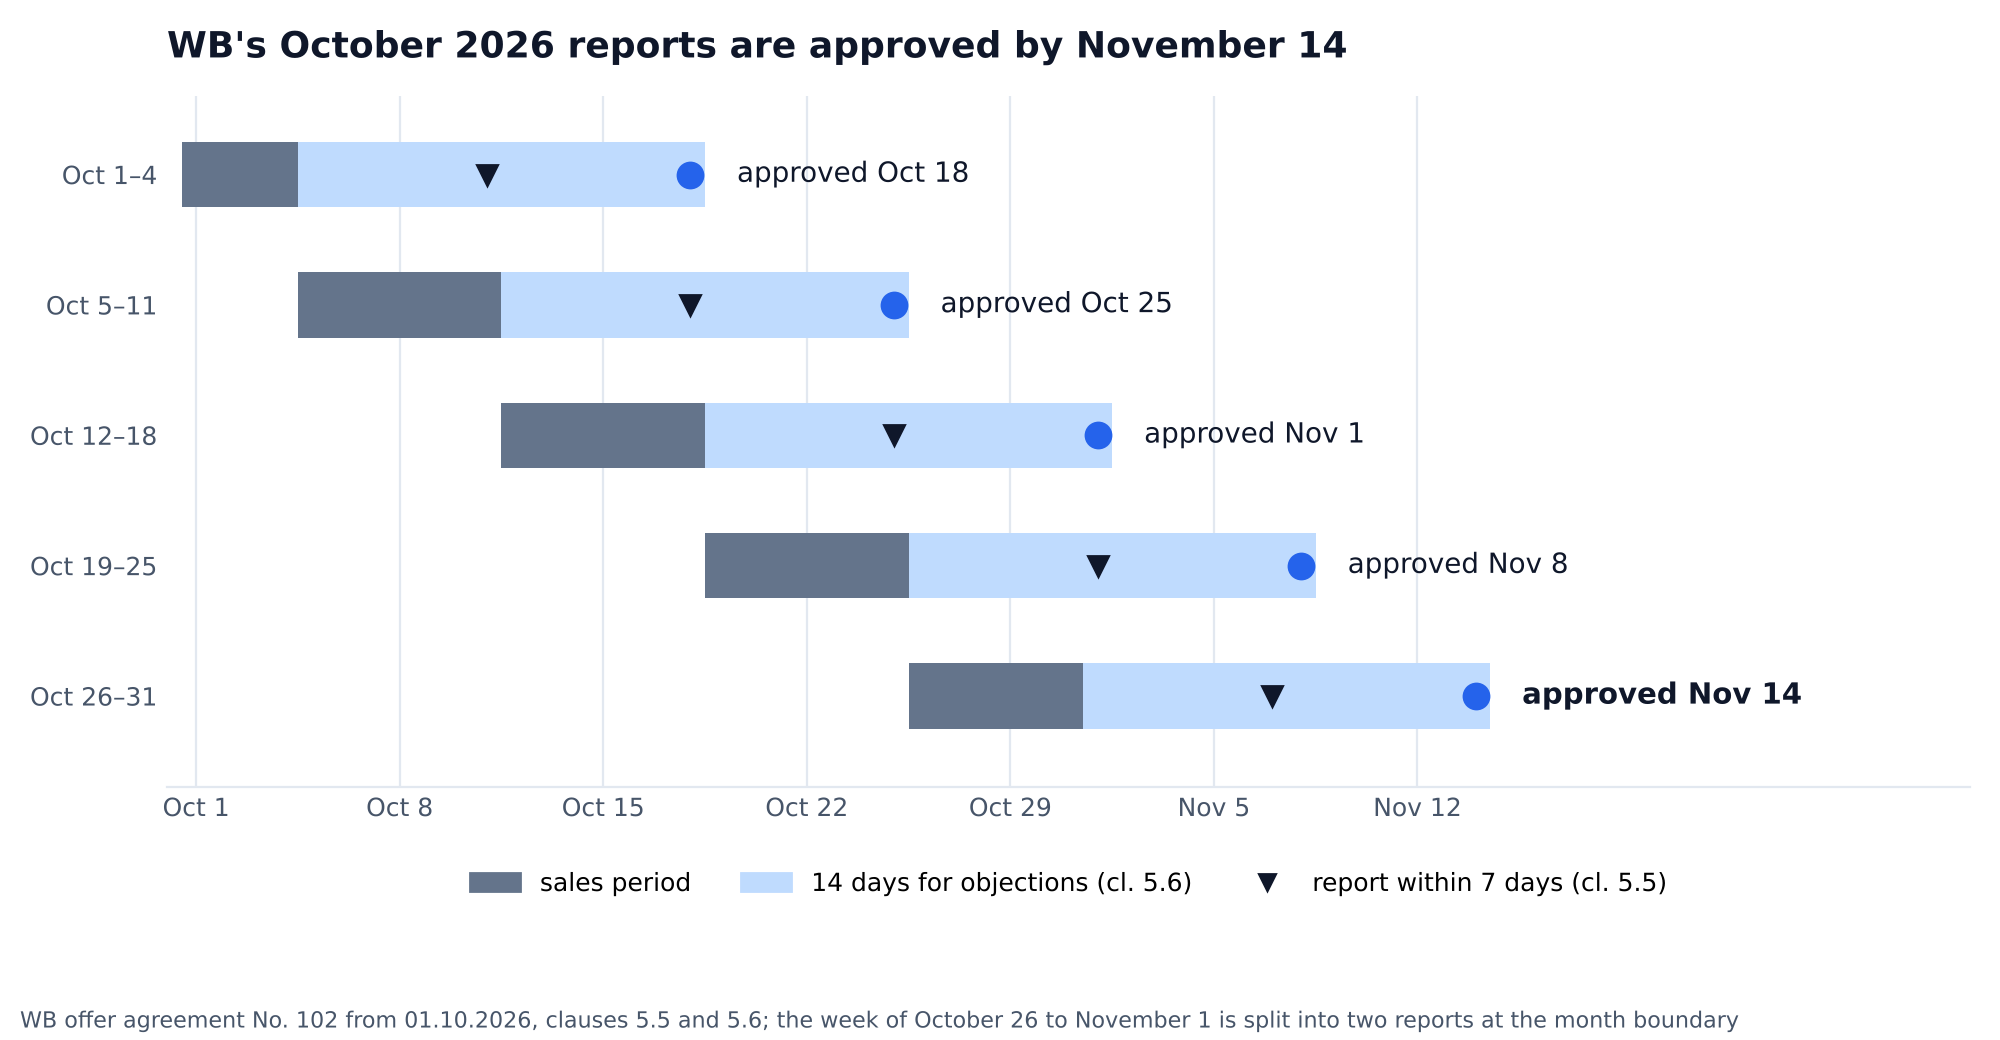
The report usually arrives ahead of the deadline: in our sample all 60 reports of one store were generated on the Monday after the week. But the 14 days for approval count from the end of the week, so the month is closed on reports not yet approved.
A caveat: for our store, the week from 23 February to 1 March 2026 came as one document, although the current offer agreement requires two. At month boundaries check the period dates in each report, and then a quarter is simply the sum of three months.
Where to find WB reports in the account
Reports sit in the "Financial reports" section of the WB Partners account, closing documents in the "Documents" section. The table shows confirmed paths only.
| What you need | Where it is | Source |
|---|---|---|
| Weekly report | "Financial reports" → "Weekly", XLSX | WB weekly report |
| Detail for 1C | Finance → Financial reports → Sales reports → Weekly → Detail | 1C:Accounting 8, 3.0.116 |
| Printable report forms | "Documents", within 7 days after the week | Self-employed on WB |
| UPD for a deduction | "Documents", search by the number from the deduction detail window | WB deductions |
| Marking UPD | "Documents", a draft within a day after the acceptance certificate | Chestny Znak on WB |
Source: the linked materials; the sources we read do not say where in the account the report on payment acceptance costs is kept
The WB acquiring report is called the "Report on payment acceptance costs" in the offer agreement. In the weekly report it matches the line "Amount withheld to secure payment processing". This is an advance, and the final amount for the month is fixed by the monthly report (cl. 12.10.1–12.10.3), more in the article on WB deductions.
WB reports for the tax office: when to recognise revenue
A seller's income under the simplified tax regime equals the buyer's full payment. The Federal Tax Service covered this case in letter SD-4-3/5416@ of 08.05.2024: a marketplace sold goods for 1,000 ₽, withheld 100 ₽ and transferred 900 ₽, and the seller's income is 1,000 ₽. Under "income minus expenses" the fee is an expense; under "income" there are no expenses.
There is no single position on the date of income.
| Position | Date of income under the simplified regime | Source |
|---|---|---|
| Ministry of Finance | When the seller gained the right to dispose of the money | Letter 03-11-11/1996 of 15.01.2025 |
| Arbitration Court of the Volga District | The day the money reaches the agent's account | 1C:ITS review of 21.03.2025 |
| WB offer agreement | The money can be claimed after the report is approved | cl. 5.7 of offer agreement No. 102 |
Source: letter of the Russian Ministry of Finance of 15.01.2025 No. 03-11-11/1996; ruling of the Arbitration Court of the Volga District of 26.02.2025 No. F06-873/2025
The difference shows at quarter end: sales of 26–31 March fall into the first quarter if you count by money reaching the agent, and may move into the second if you wait for the report to be approved. Choose a rule with your accountant and stick to it.
Example: how to book one week of the report
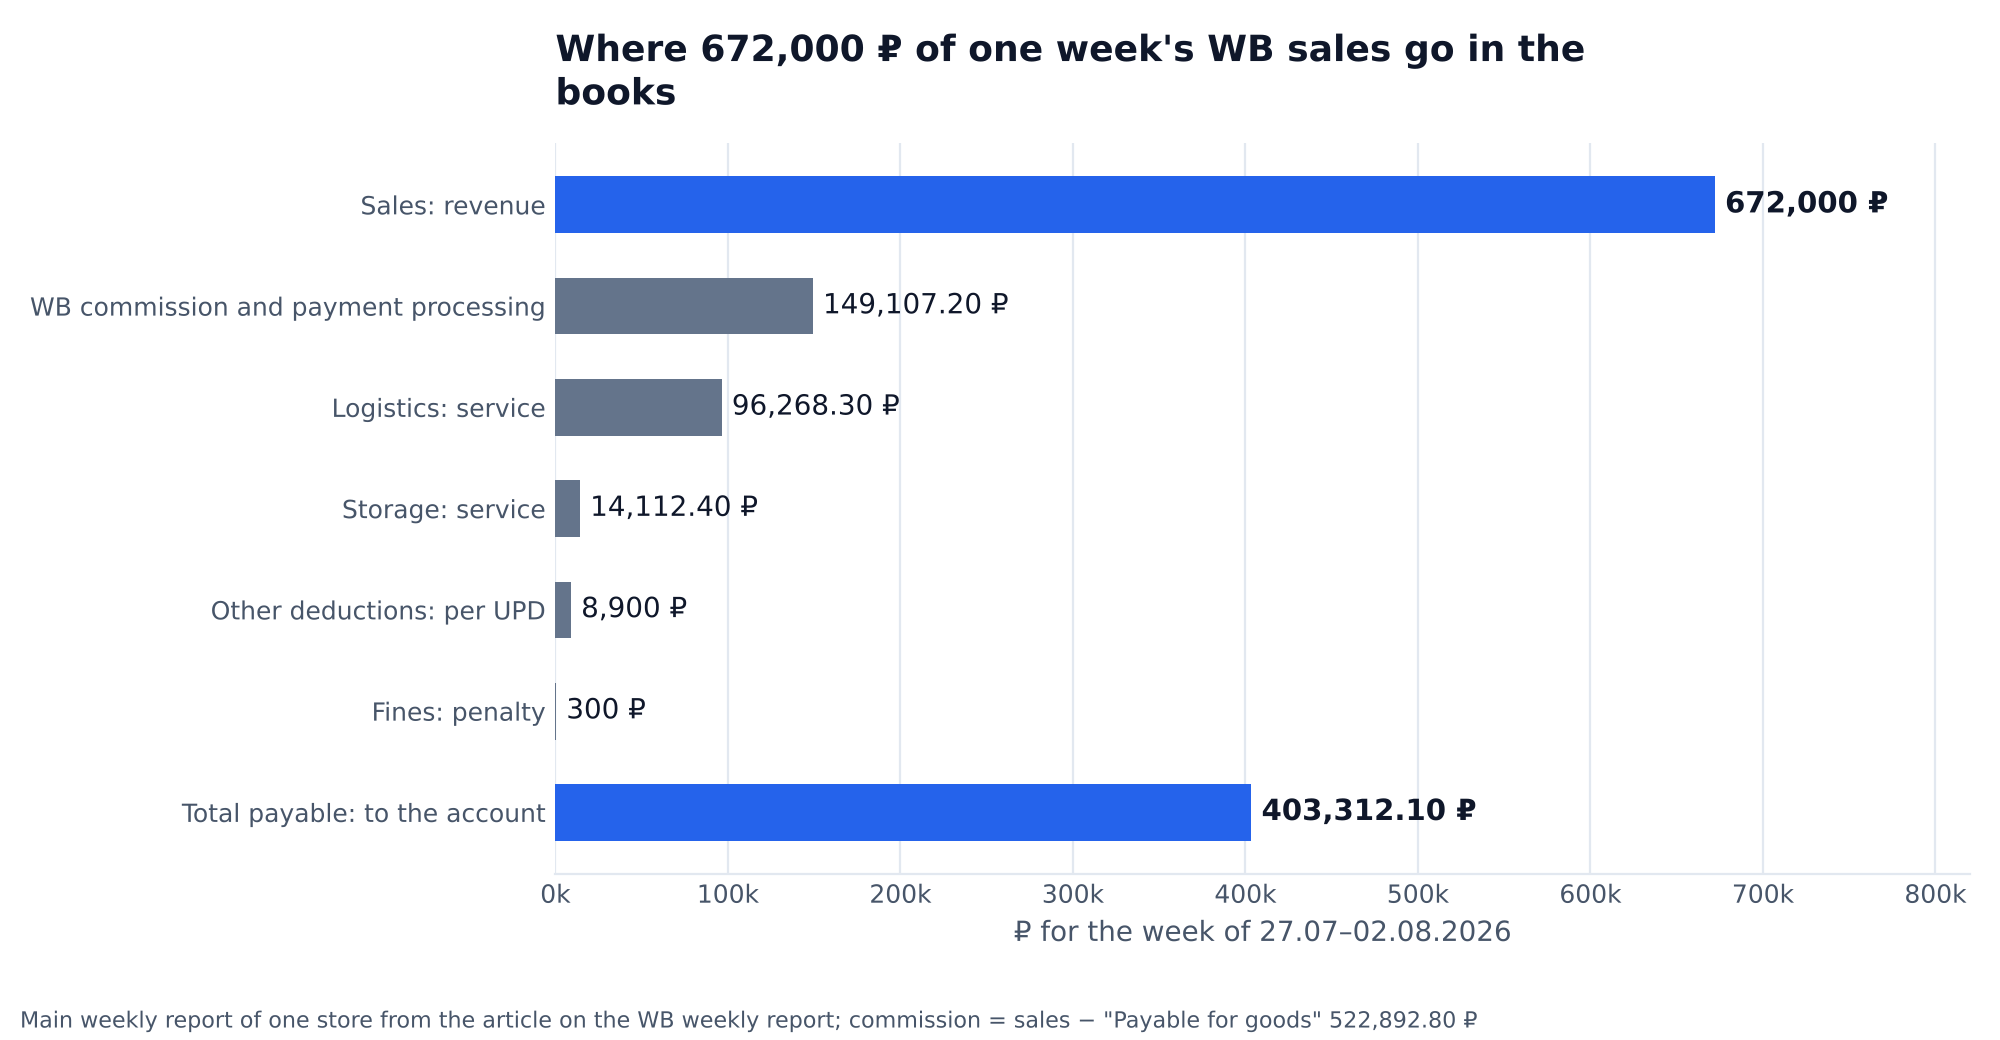
Take the main report for the week from 27 July to 2 August 2026 from our weekly report breakdown. Buyers paid 672,000 ₽, 403,312.10 ₽ reached the account, and the difference has to be split by document.
| Report line | Amount | Where it goes in the books | Basis |
|---|---|---|---|
| Sale | 672,000.00 ₽ | Revenue, income under the simplified regime | Agent's report |
| WB commission and payment processing | 149,107.20 ₽ | Fee and costs | Report, monthly cost report |
| Logistics and storage | 110,380.70 ₽ | WB services | Report (cl. 6.7) |
| Other deductions | 8,900.00 ₽ | Per UPD for the deduction | "Documents" section |
| Penalties | 300.00 ₽ | Penalty | Report detail |
| Total payable | 403,312.10 ₽ | Bank reconciliation | WB payment |
Source: the store's main report for 27.07–02.08.2026 from the article on the WB weekly report; commission = 672,000 − 522,892.80 ₽ "Payable for goods"
Under the 6% "income" regime the tax for the week is 40,320 ₽. Calculated on the payout it would be 24,198.73 ₽, and the 16,121.27 ₽ difference for a single week turns into an additional assessment. One more subtlety: the week crosses 31 July, so for monthly books the sales of 1–2 August go to August by the dates in the report detail.
How to post a WB report in 1C
In 1C:Accounting 8 edition 3.0, marketplace sales are handled with documents from the "Sales → Sales → Marketplaces and commission agents" menu of the full interface, as described in the 3.0.116 release notes. A WB report loads into the document from version 3.0.114, and from 3.0.140.40 you can load several files or an archive.
| Operation with WB | 1C document | Item in the "Marketplaces and commission agents" menu |
|---|---|---|
| Shipping a supply to a WB warehouse | Sale, "Transfer for sale" | Transfer for sale |
| Sales and returns from the report | Commission agent report on retail sales | Sales report (retail sales) |
| Lost goods and compensation | Commission agent write-off report | Write-off report (write-off certificate) |
| WB fee and services | Receipt of services | Receipt of services (certificate, UPD) |
Source: "1C:Accounting 8. What's new in versions 3.0.114, 3.0.116 and 3.0.140.40", its.1c.ru; requires the flag "Sale of goods or services through commission agents (agents)"
As 1C experts explain on BUKH.1C, the retail commission agent report records only sales and returns, so the fee is posted separately. The full "Commission agent (agent) sales report" with the fee and VAT invoices is needed when the intermediary issues VAT invoices to buyers. If the WB detail contains write-offs, the program creates the write-off report itself, and items are matched by hand on the first load.
Whether the payout matches the report is shown by the "Payout reconciliation" tab in Parus Seller. The first two months are free with promo code PARUS60: connect your account.
Frequently asked questions
How do I post a WB report in 1C? Load the weekly report detail into the "Commission agent report on retail sales", and post WB services with a "Receipt of services" document.
Which WB reports does the tax office need? The weekly sales reports: the "Sale" column is income under the simplified regime. Under "income minus expenses" the WB fee reduces the base.
What is the WB acquiring report? It is the "Report on payment acceptance costs" under cl. 12.10 of the offer agreement. WB sends it per month and counts the weekly acquiring deductions against it as an advance.
What happens if I do not sign a UPD from WB? For promotion and delivery on return, after 3 working days without objections the services are deemed accepted. For promotion, claims on volume and cost are no longer accepted after that (cl. 15.6.1).